Why Is the Lessor Named on My Policy
The lessor is named because it owns the car and has a financial stake in it until you pay off or return the lease.

A fender bender that became a paperwork lesson
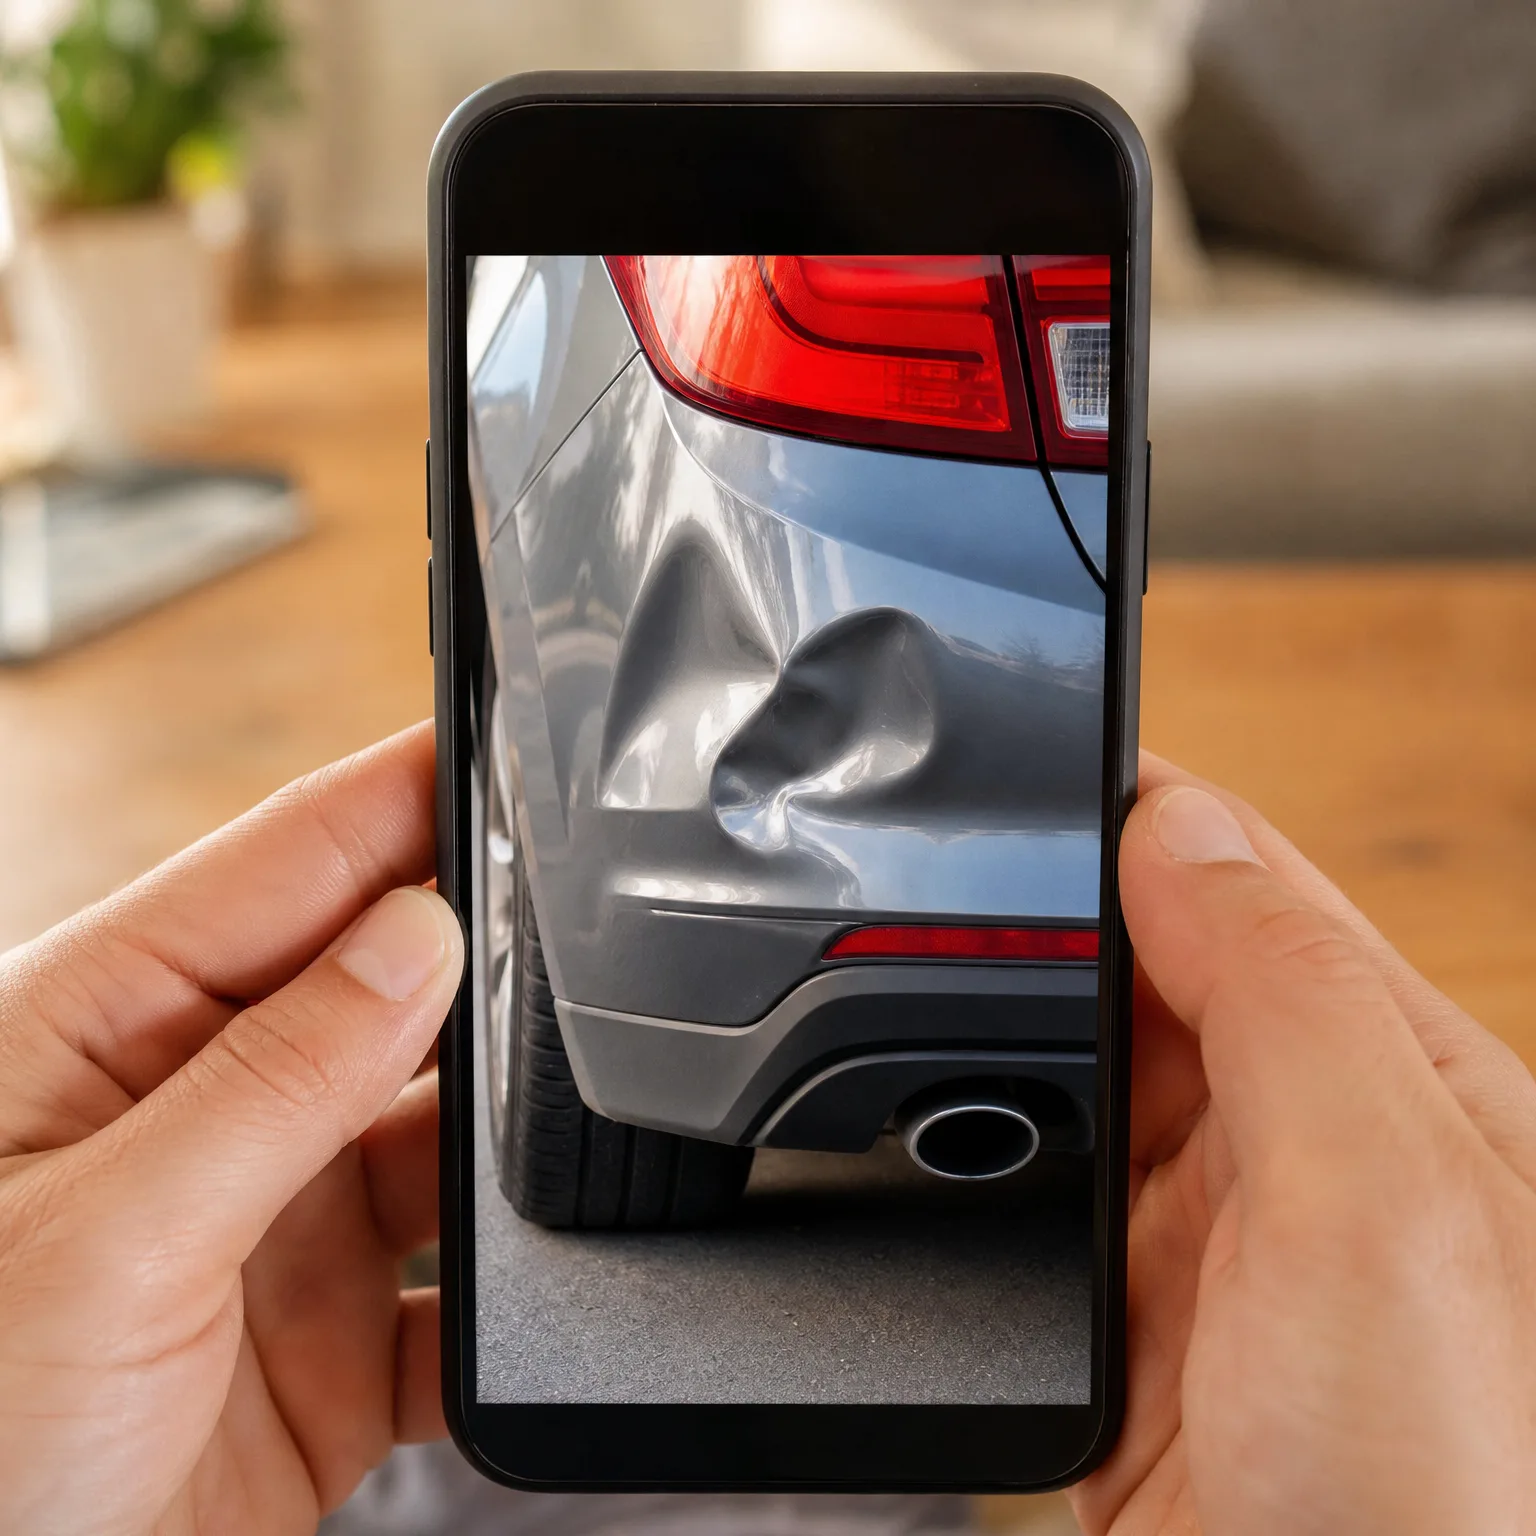
A reader leased a sedan and six months later got hit in a parking lot. The repair shop estimate came in high enough that the insurer considered the car a near-total loss. Because the leasing company was listed as an additional interest on the policy, the claims adjuster had to loop them in before any payout went out. The reader hadn't realized this was normal and briefly panicked, thinking something had gone wrong with their coverage.
It turned out the lessor just needed confirmation that the policy was active and that repair or payout funds would go toward the car's value, not straight to the reader. The adjuster explained that this protects the lessor's ownership stake, since they're the ones who'd lose money if the car were repaired poorly or not repaired at all. The repair went through, the car was fixed, and the lease continued as if nothing happened. The only real difference from an owned car was an extra name on some paperwork and a short delay while everyone confirmed coverage was in place.
Does naming the lessor change who gets the insurance payout?
Yes, in the sense that the payout for a total loss or major damage claim is directed with the lessor's interest in mind, not handed straight to you. The lessor doesn't collect the money for themselves. Instead, the insurer makes sure the car gets repaired properly, or if it's totaled, that the lease balance gets paid off before any remaining money comes to you.
This is standard for any financed or leased vehicle, not something specific to your insurer or your lease terms. If you owned the car outright, the payout would go directly to you instead. The arrangement exists because the lessor still legally owns the car, so they have a right to make sure their asset is protected or made whole.
The lessor isn't watching you, they're protecting a car they own, and that shapes your coverage.
Once you know why the lessor is listed, compare quotes that meet the lease's requirements without overpaying.
The lessor's name protects their ownership, not your driving record
When you lease a car, you're essentially renting it long term while the leasing company retains legal ownership. That ownership is why they show up on your insurance policy as an additional interest or loss payee. They want written proof that if something happens to the car, there's a financial safety net that repairs it or pays off its value, because it's still their asset on paper.
This differs from being named as an additional insured, which is a separate status that sometimes also appears on lease paperwork. An additional interest just means they get notified about major changes to your coverage, like cancellation, and have a claims interest. An additional insured status, less common on personal leases, could extend some liability protection to the lessor too. The paperwork should specify which one applies, and if it's unclear, that's worth asking about directly.
In most cases, this setup doesn't change your day to day experience. You still file claims the same way, still deal with the same adjuster, and still make repair decisions. The difference shows up mainly in total loss situations, where the insurer coordinates payout handling so the lease balance gets addressed first. If there's money left over after that, it comes to you.
What varies by state and by leasing company is how strictly this gets enforced and what specific wording appears in your policy. Some lessors require specific coverage types or notification procedures beyond the basics. Check your lease agreement's insurance section and compare it against your policy's declarations page to make sure the right name and status appear correctly.
What happens if I don't add the lessor to my policy?
Your lease could be in default, since most leasing companies require this as a condition of the agreement. The leasing company may find out through their own records matching or during a claim, and either way could force-place expensive coverage on your behalf or demand proof immediately. Check your lease contract for the exact insurance requirements and add the lessor as soon as you set up your policy.
Can I remove the lessor from my policy before the lease ends?
No, not while you still owe on the lease and don't own the car outright. The lessor stays listed as long as they hold the title, which is the entire lease term unless you buy out the car early. Once you either buy out the lease or return the car at the end, you'd update your policy to remove them and reflect new ownership or no vehicle at all.
Does the lessor get notified if I let my insurance lapse?
Yes, most lessors require the insurer to notify them of cancellations or lapses, which is part of why they're listed on the policy. This notification clause protects their investment by giving them a chance to act before a gap in coverage becomes a real problem. Check your lease agreement for how much notice they receive and what they're allowed to do, like force-placing coverage, if you don't fix the lapse quickly.